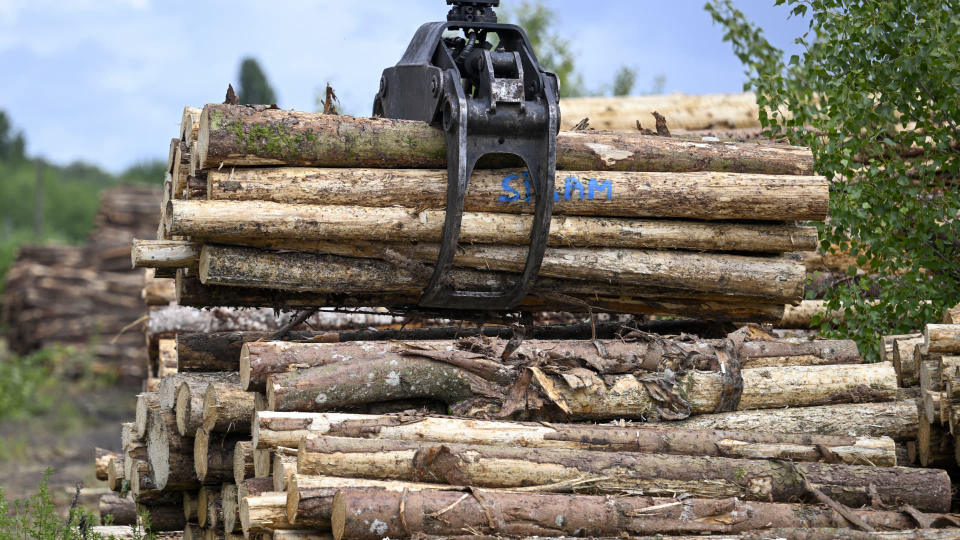
Investors are buying up vast tracts of timberland across U.S. in one of market's longest-term bets
Timberland managers buying for pension funds and other institutional investors can wait decades for returns, but the market can also be a profit trap.
Key points
- Institutions have been buying timberland at about one million acres a year, a pace Bank of America expects to continue.
- Advisors warn timber offers low short-term returns, with supply outpacing demand in a sluggish housing market.
- Timber ETFs offer liquid exposure to timber-related companies but do not own land or trees directly.
Institutional investors have been acquiring timberland across the U.S. at a rate of about one million acres per year, according to Bank of America, which reported a three-year streak of dealmaking it expects to continue. The bank's 2026 outlook said timber managers bought 55% of all acres that changed hands in 2025, against just 15% sold.
Some financial advisors say individual investors, including younger Americans priced out of the housing market, are also looking at the asset class, though it is far from a rush. Investors who already own timberland caution that it may not be very profitable in the short term.
Why owners urge caution
Pat Dorn, founder of Anchor Investment Management in Columbia, South Carolina, owns 2,500 acres of timberland and said more timber is being grown than is needed in a sluggish housing economy. "Supply beats demand, and that causes flat prices," he said, adding that timber is not an investment he would make currently.
South Carolina Forestry Commission data show statewide average pine pulpwood stumpage prices fell about 33% between the third quarter of 2025 and the third quarter of 2026, from $5.67 to $3.79 a ton. Pine sawtimber fell about 6%, from $22.78 to $21.47 a ton, while hardwood sawtimber rose about 40%, from $16.04 to $22.52.
The return is in the land, not the timber
— Pat Dorn
Long-term view and risks
Ken Shepard, head of specialty asset management at Bank of America Private Bank, said timberland is not a tactical asset class and described it as "a strategic, long-term investment" supported by trends including expansion of the timber industry in the U.S. South and growing demand for wood products beyond construction.
Michael Martin, a timber owner in western New York, said direct ownership is highly illiquid and carries management costs, property taxes, harvesting expenses and risks including wildfire, pests, disease and trespassers. He said partial timbering every ten years or so has barely covered his property taxes: "At the end of the day, I barely break even."